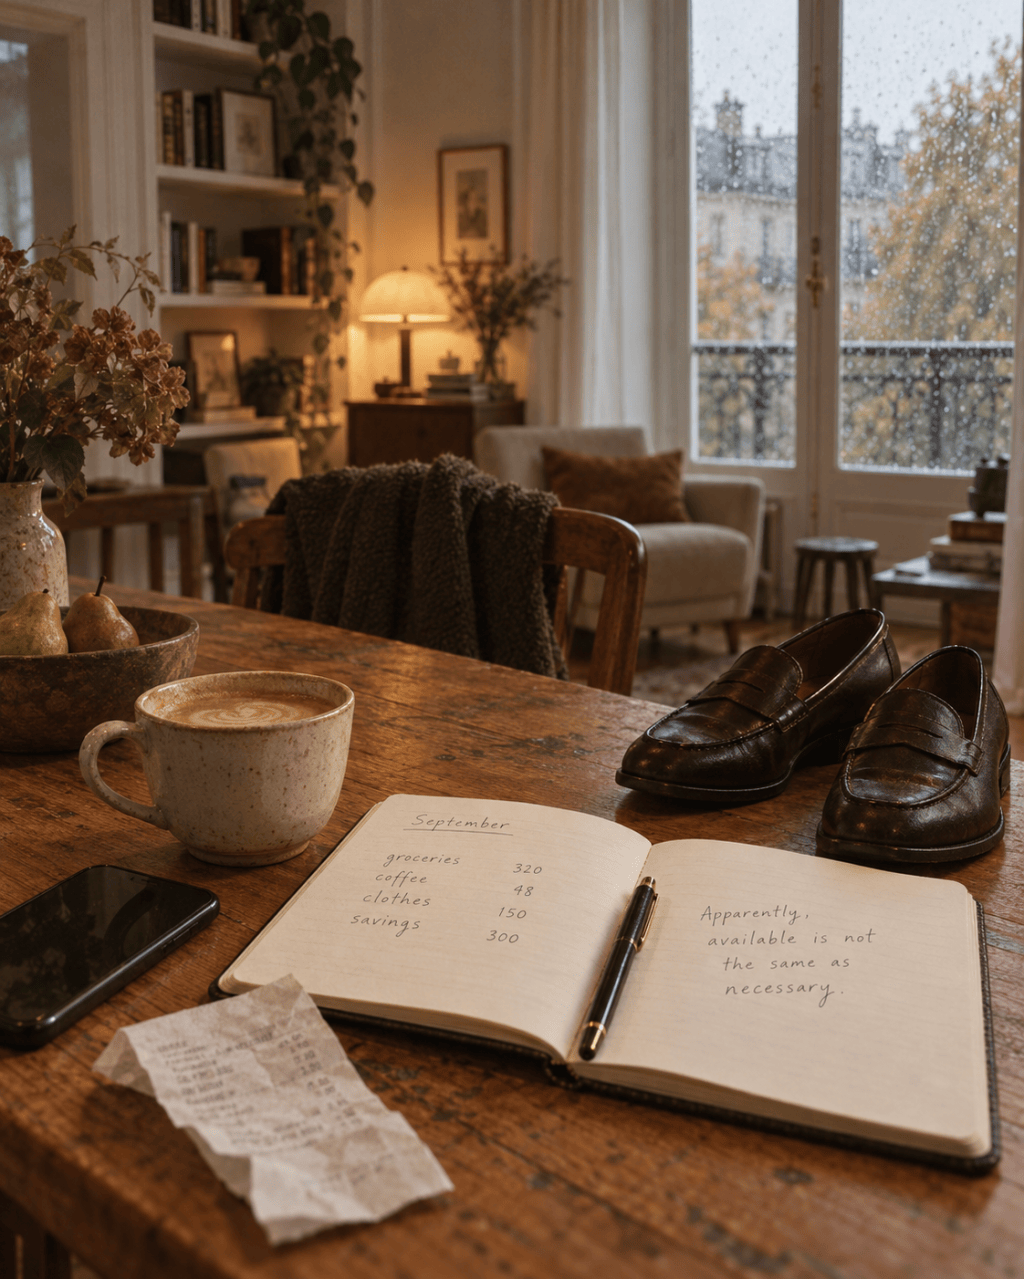
A few months ago, I decided to become the sort of person who has budgets.
Not a budget in the vague sense of knowing roughly what comes in and trying not to behave like a minor European monarchy until payday, but actual little pots for things. Groceries have a pot, the hairdresser has a pot, restaurants have a pot, clothes have a pot, and even coffee has a pot now, which feels slightly insulting considering how long coffee and I have been together.
The idea is very sensible. If the hairdresser costs a certain amount every three months, I put a third of that amount aside every month, and when the appointment comes around the money is simply there. The same goes for expenses I know are coming, while a fixed amount goes into savings every month and, crucially, is supposed to stay there.
For years, I was very good at transferring money to my savings account and considerably less committed to the concept of leaving it there. Technically I was saving, but I was also unsaving whenever something came along that I wanted badly enough, which turns out to be a surprisingly ineffective long term financial strategy.
It is strange, because when I started working in education at twenty one, I earned a fraction of what I earn now and somehow managed to live perfectly well. I had bought an apartment on my first proper salary, an idea my mother considered somewhere between wildly optimistic and completely insane, and yet every month the mortgage was paid, there was food in the fridge and life continued.
Admittedly, life was cheaper then. I also don’t remember everyone constantly meeting for coffee, lunch, dinner, brunch and whatever meal we’ve invented between lunch and dinner because apparently simply sitting in somebody’s living room has fallen out of fashion.
Now I earn considerably more, and somehow there are months when my bank account behaves as though I’ve spent the past four weeks financing a small infrastructure project.
Hence the pots.
For the most part, they are working brilliantly. They make me much more aware of what I’m spending, particularly on groceries, which have reached the point where leaving a supermarket with three bags and ninety euros less feels like a reasonably successful trip. I’ve started noticing all the tiny differences too. The individual high protein drinks I used to buy without thinking are considerably more expensive than buying a litre carton, so now I buy the carton and feel briefly like a financial genius for having discovered multiplication.
There is, however, one flaw in my new system, and that flaw is me.
I gave myself a clothing budget of €150 a month because that seemed reasonable, even though I don’t actually buy clothes every month. I tend to do it in phases, where suddenly clothes are interesting again and several things enter my wardrobe within a few weeks, followed by months in which I couldn’t care less.
Before the budget, this worked surprisingly well because if I didn’t want anything, I bought nothing. Now I open my banking app, see €150 sitting obediently in the clothing pot and find myself wondering what we’re going to do with it, as though the money has arrived specifically requesting entertainment.
Apparently I have accidentally turned a spending limit into a monthly challenge.
I have therefore had to explain to myself that €150 available for clothes does not mean I am contractually obliged to spend €150 on clothes. It is permitted to remain there, it can even accumulate, and after several decades of managing my own finances I am pleased to report that I have rediscovered the basic principle of saving.
Restaurants are proving slightly more complicated because budgets are very good at dealing with numbers and considerably worse at dealing with friends.
Last month I took a friend out for a rather lovely fine dining dinner, which used up pretty much my entire restaurant budget in one go. Financially, this was exactly what the pot was for, but socially it means that if someone subsequently asks whether I fancy dinner, I have to resist the slightly absurd feeling that saying, “I’d love to, but can we do next month?” makes me sound as though I’m one unexpected bill away from selling a kidney.
I’m not, of course. I’ve simply spent the amount I decided I wanted to spend on restaurants that month, and there is an enormous difference between not being able to afford something and deciding that you have already spent enough on it, although I am discovering that the second one can be strangely difficult to say out loud.
Perhaps we have also become very accustomed to socialising with a debit card attached. A coffee becomes lunch, a walk somehow ends on a terrace, catching up means dinner, and before you know it you’ve spent €47 because somebody wanted to hear how your week was. We used to go to each other’s houses, where, unless my memory is failing me completely, coffee was also available.
Then there are the expenses that refuse to fit neatly into any of my beautifully organised categories. My cats, for instance, have apparently never seen my spreadsheet. Two dental procedures can suddenly cost around €1,800, and while I deliberately put money aside for them years ago instead of taking out insurance, it still feels faintly offensive when two small naked creatures manage to generate a bill that would fund quite a respectable weekend away.
The apartment has similar ideas. I have lived here for about seventeen years now, and although I’ve changed colours, furniture and various other things over the years, the kitchen, bathroom and toilet are essentially the originals. They are still perfectly usable, but I’ve reached the stage where I occasionally look at the kitchen and wonder whether we’re growing old together.
The floors have also survived ten years of cats, including incidents we needn’t revisit, and at some point the question becomes whether I start properly renovating things or continue what I prefer to call strategic maintenance until I decide whether I actually want to stay here.
Because renovating properly is not a new lamp and a tin of paint. Once you start talking about a kitchen, bathroom, toilet and floors, €50,000 can disappear with an efficiency I would quite like my mortgage to learn.
This is perhaps the one financial lesson I genuinely would give my twenty one year old self. She had understood that buying a home meant paying a mortgage every month, but nobody had really impressed upon her that one day the perfectly good kitchen she was standing in would become a seventeen year old kitchen, and that Future Sophie might appreciate it if Past Sophie had been putting a little money aside for that eventuality. Then again, she had just bought an apartment on her first salary against considerable maternal scepticism, so I suspect she would have considered herself perfectly capable of handling the situation.
The latest thing I have decided not to buy is winter tyres.
Last winter I discovered during the snow that my car, fitted with summer tyres, does not share my enthusiasm for arriving at work safely in all weather conditions. Since I no longer work in the town where I live, I decided that this year I would be sensible and buy a separate set of decent winter tyres with their own rims, so they could simply be changed over each season.
Then I discovered that I would be looking at roughly €1,500.
At €1,500, my newfound financial discipline very quickly produced an alternative transport strategy involving public transport. If it snows, I’ll take the train or RandstadRail, and if that takes longer I’ll leave earlier, because there comes a price point at which being slightly inconvenienced by Dutch public transport begins to look remarkably luxurious.
And perhaps that is what I’m actually learning from all these little pots. I haven’t suddenly become someone who considers a takeaway coffee an act of financial recklessness, and I still want the lovely dinner, the occasional clothes, the recipes that require ingredients I don’t already own and the latte made by somebody who knows my order before I’ve said it. I just don’t particularly want to reach the end of another year wondering how I managed to earn considerably more than I did at twenty one while still being capable of making money disappear with roughly the same efficiency.
The clothing pot currently has €150 in it, though, and I have seen a very nice pair of shoes.
So perhaps we shouldn’t congratulate me just yet.
-Sophie Quinn



Leave a Reply